2026-09-08 13:01:00
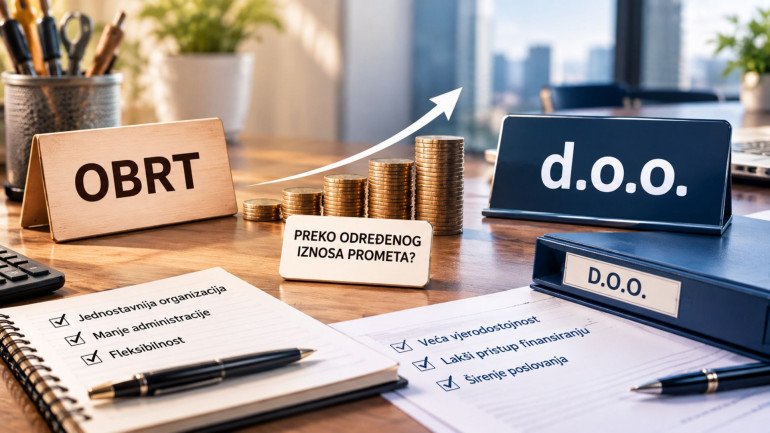
Is there a revenue threshold after which you MUST switch from a craft to a d.o.o. (LLC)?
Where Does the Misconception About "Mandatory Switching" Come From?
Entrepreneurs often confuse three completely different legal concepts:
-
Threshold for losing flat-rate tax status (FBiH Personal Income Tax Law)
-
Statutory threshold for mandatory entry into the VAT system (BiH VAT Law)
-
Switching from a craft to a limited liability company (d.o.o.)
When a craft owner exceeds a certain revenue threshold, the law does not force them to open a company; instead, it changes their tax and accounting treatment:
-
Exceeding the limit for flat-rate taxation: If you operate as a flat-rate craft owner, exceeding the prescribed annual income/revenue limit causes you to lose the right to flat-rate taxation. This does not mean you must open a d.o.o.; rather, you have a legal obligation to switch to regular bookkeeping (maintaining the Book of Revenues and Expenses – KPR, Book of Turnover – KP, and Book of Fixed Assets – KOS) with taxation applied to the actual difference between collected revenues and paid expenses at a rate of 10%.
-
Exceeding the VAT system threshold: When the taxable turnover of a craft in the previous 12 months exceeds the legally defined threshold (100,000 KM), the craft owner is obligated to submit an application to the Indirect Taxation Authority (ITA BiH) for VAT registration. A craft can operate entirely legally within the VAT system – turnover can reach hundreds of thousands of marks while you remain registered solely as a craft.
If the Law Does Not Require a Switch, WHEN and WHY Should a Craft Be Converted to a d.o.o.?
Although no one administratively forces you, in practice, there are four key reasons why significant business growth dictates a transition to a d.o.o.:
-
Risk and Personal Assets (The Most Important Factor)
-
In a craft: The owner guarantees all business debts, unpaid tax obligations, suppliers, and loans with their entire personal assets (house, apartment, private bank accounts, car).
-
In a d.o.o.: The owner is liable exclusively up to the amount of the registered share capital. The founder's personal assets are completely separate and protected from business risks. As turnover and contract volumes grow, so does the risk—which is no longer wise to carry on private shoulders.
-
-
Tax Mathematics and Profit Reinvestment
-
In a craft: All generated net income (income after recognized expenses) is taxed with a 10% income tax, and the money belongs to the owner. However, in a craft, there is no concept of retained (undistributed) profit for further capital investments in the same tax sense as in corporations.
-
In a d.o.o.: The company pays corporate income tax (10%). Profit can be retained in the company's bank account for new investments, development, hiring, or purchasing equipment, without the need to immediately pay it out to the owner.
-
-
Credibility with Major Partners and Import/Export
-
Larger domestic and foreign companies, corporations, and banks often have internal policies under which they assign higher-value contracts exclusively to legal entities (d.o.o. or d.d.). Furthermore, foreign trade operations (exports, bonded warehouses, larger imports) and participation in public procurement tenders are significantly simpler and more natural to conduct through a corporation.
-
-
Hiring More Workers and Expanding Structure
-
When a business grows to more than 5 or 10 employees, managing personnel records, payroll calculation, occupational health and safety, and business organization become complex. For such an operational structure, the d.o.o. form provides a better legal and organizational platform.
-
Can a Craft Simply Be "Converted" into a d.o.o.?
In the legal system of the Federation of BiH, there is no form or process by which a craft is simply "renamed" into a d.o.o.
The process involves:
-
Registering a new legal entity (d.o.o.) at the competent municipal court by drafting founding documents, paying the initial capital, and obtaining a new ID and VAT number.
-
Transferring operations, new contracts, and partners to the d.o.o.
-
Executing the legal procedure for closing or deregistering the craft with the municipal service and the Tax Administration of FBiH (or retaining the craft if a justified business model exists for both entities).
This process requires synchronized work among an accountant, tax advisor, and attorney to avoid business interruptions, delays in fiscalization, or issues with transferring inventory and equipment.
Why Choose Agencija Poslovnost d.o.o. Sarajevo? Everything Under One Roof
The decision to transition from a craft to a d.o.o. is never made hastily. It requires a precise financial calculation so you know exactly what your costs, contributions, taxes, and administrative obligations will be.
Through the "Everything Under One Roof" concept, Agencija Poslovnost d.o.o. Sarajevo enables a seamless transition:
-
Bookkeeping and Accounting Services: Detailed analysis of your business operations, bookkeeping (KPR/KP or double-entry accounting), closing balance sheets for the craft, and opening balance sheets for the d.o.o.
-
Tax Consulting: Calculation of the tax efficiency of switching to a d.o.o., preparation for entering the new d.o.o. into the VAT system, and tax optimization.
-
Legal Support and Attorneys: Preparation of complete documentation for the court register, drafting of founding acts, employment contracts, and handling the craft deregistration process.
-
Software Companies and Authorized Fiscalizers: Transferring or implementing new accounting software, moving the fiscal cash register to the new legal entity, and providing technical support without sales interruptions.
Do not guess when the right moment to change your legal form is – consult experts and make a decision that protects your assets and accelerates business growth.
🏢Agencija Poslovnost d.o.o.
📧info@poslovnost.ba
📞033/246-421
📍Kotromanića 48, Sarajevo
More Posts
2026-09-08 12:48:00
Classification of Sole Proprietors in FBiH: Freelance Professions, Craft Activities, and Contribution Base Amounts
One of the most important financial issues when establishing and operating an independent business in the Federation of Bosnia and Herzegovina is determining the exact category of sole proprietorship and the amount of monthly fixed contributions. According to the FBiH Law on Contributions and the annual Order of the Federal Ministry of Finance, owners of independent businesses do not pay contributions at the same rate, but are instead classified into different categories based on the type of work and professional qualifications. Below is a detailed guide to the legal classifications of independent business owners in FBiH, the method for determining monthly bases, and the role that a licensed accountant and a professional bookkeeping service play in proper calculation and tax optimization.
More
2026-09-02 13:04:00
Bookkeeping and Accounting Services in FBiH: Rights and Responsibilities of a Sole Proprietorship Owner
Starting and operating an independent business activity or a sole proprietorship in the Federation of Bosnia and Herzegovina brings numerous operational advantages—from a simpler registration process to more flexible management of cash funds compared to limited liability companies (d.o.o.). However, conducting business as a sole proprietorship involves a specific legal and financial status, as the personal identity of the owner is legally inseparable from the business itself. Compliance with the FBiH Law on Crafts and Related Activities, the FBiH Law on Income Tax, fiscalization regulations, and the Decree on Cash Payments enforces strict business rules. Any lack of knowledge of legal norms, delays in submitting forms, or the absence of expert support provided by a professional bookkeeper and licensed accountant directly exposes the owner's personal assets to heavy fines and forced collection.
More