2026-09-21 08:44:00
Tax-Deductible and Non-Deductible Business Expenses: What Can Be Charged to the Company Account and What Incurs Fines?
Basic Rule: Which Expenses Are Tax-Deductible?
For a specific invoice or expense to be recognized in the accounting books, it must satisfy three key conditions:
-
Business Purpose: The expense must be directly linked to performing the registered business activity and aimed at generating revenue.
-
Authentic Documentation: Every expense must be supported by a valid fiscal receipt, an invoice issued to the legal entity (with the tax ID / JIB and full company name), and supporting documents (e.g., delivery note, work order, contract, job completion report).
-
Principle of Reality: The goods or services must actually be delivered and utilized for the company's operational needs.
Representation Expenses: Where Is the Limit?
Restaurant bills, coffees, business lunches, and gifts for business partners fall under representation expenses. Special legal rules apply to these expenditures:
-
In the Federation of Bosnia and Herzegovina, representation expenses are recognized at 30% of the total expense, while the remaining 70% is considered non-deductible and increases the corporate tax base.
-
The VAT included in representation receipts cannot be claimed as input tax credit.
-
For a hospitality bill to be accepted at all, the business purpose of the meeting and details of the business partners present must be specified on the back or attached to the invoice.
Business Travel and Travel Orders
Expenses for business travel (per diems, overnight stays, fuel, tolls) are a frequent target of tax audits. To be tax-deductible:
-
A properly filled out and signed travel order is mandatory, containing accurate details regarding the destination, purpose of the trip, departure, and return times.
-
A written business trip report proving the commercial outcome must be attached to the travel order.
-
Valid receipts issued to the company name must exist for accommodation and transportation.
-
If a travel order or report is missing, tax authorities may disallow the expense and reclassify the paid per diems as taxable income of the employee or director.
Company Vehicles: Fuel, Registration, and Maintenance
Automobile expenses are recognized depending on how the vehicle is registered and used:
-
Commercial and Delivery Vehicles: All expenses (fuel, servicing, depreciation) are generally 100% tax-deductible, and input VAT can be claimed if used exclusively for business.
-
Passenger Vehicles Owned by the Company: Expenses for business usage are recognized, but detailed usage logs (vehicle logs, mileage tracking) must be maintained. If used for personal purposes by employees, a benefit-in-kind must be calculated.
Most Common Non-Deductible Expenses Made by Entrepreneurs
During the annual tax return and balance sheet preparation, your accountant must exclude the following items from deductible expenses:
-
Personal Expenses of Founders or Directors: Purchase of clothing, personal groceries, paying for family vacations, or household utility bills using the company account.
-
Default Interest and Fines: Monetary fines imposed by inspections, tax authorities, or courts are never tax-deductible.
-
Donations and Sponsorships Exceeding Legal Limits: Expenses for humanitarian, cultural, and sports purposes are recognized only up to a legally defined percentage of total revenue from the previous year (up to 3%). Anything exceeding that cap is non-deductible.
-
Inventory Shortages: Shortages that exceed prescribed standards (shrinkage, waste, damage) are treated as extraordinary expenses and subject to taxation.
-
Obsolete and Written-Off Receivables: Customer receivables that have not been legally pursued or secured within prescribed statutory deadlines cannot be automatically written off to expenses without tax consequences.
How Professional Accounting Saves You Money
Incorrect recording of expenses directly threatens business operations: if you claim what the law prohibits, you risk inspection fines; if you fail to claim legitimate expenses, you will pay more corporate tax than owed.
As part of the "All Under One Roof" concept, the agency Poslovnost d.o.o. Sarajevo helps businesses establish precise documentation control. Our team of accountants and tax advisors guides clients daily on legally justifying every invoice to achieve optimal tax savings.
📧info@poslovnost.ba
📞033/246-421
📍Kotromanića 48, Sarajevo
More Posts
2026-09-21 08:32:00
Dividend Distribution in a LLC (d.o.o.) in FBiH: When, How, and with What Tax Obligations?
One of the main goals of every successful entrepreneur is making a profit. However, when a limited liability company (d.o.o.) achieves a positive financial result, a key question arises for the founders: How can the earned money be legally, safely, and without tax risks paid out to a private account? In practice, it often happens that company owners withdraw money or make transactions without a valid legal basis, which the tax inspection can treat as a disguised payout of profit or taxable income, along with default interest charges and high fines. That is precisely why the role of a professional accountant is crucial to ensure every step is carried out strictly in accordance with the law. Below, we present a detailed overview of the conditions, procedures, and tax treatment for the payout of profit in the Federation of Bosnia and Herzegovina.
More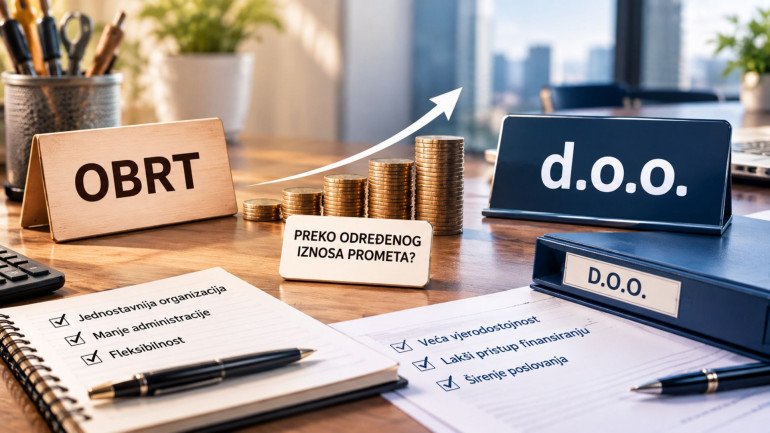
2026-09-08 13:01:00
Is there a revenue threshold after which you MUST switch from a craft to a d.o.o. (LLC)?
One of the most common questions and dilemmas faced by successful craft owners in the Federation of Bosnia and Herzegovina is: "My business is growing, my revenue is increasing – is there a legally prescribed revenue threshold after which I must close my craft and establish a d.o.o. (LLC)?" Below is a detailed analysis of why this misconception arises, which key thresholds you must track, and when is the right moment to switch to a d.o.o.
More